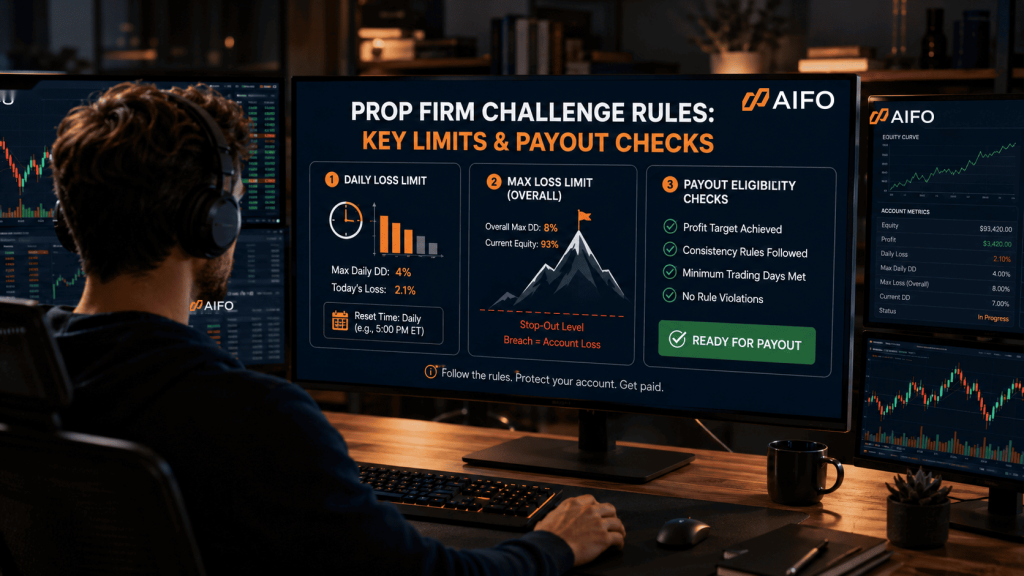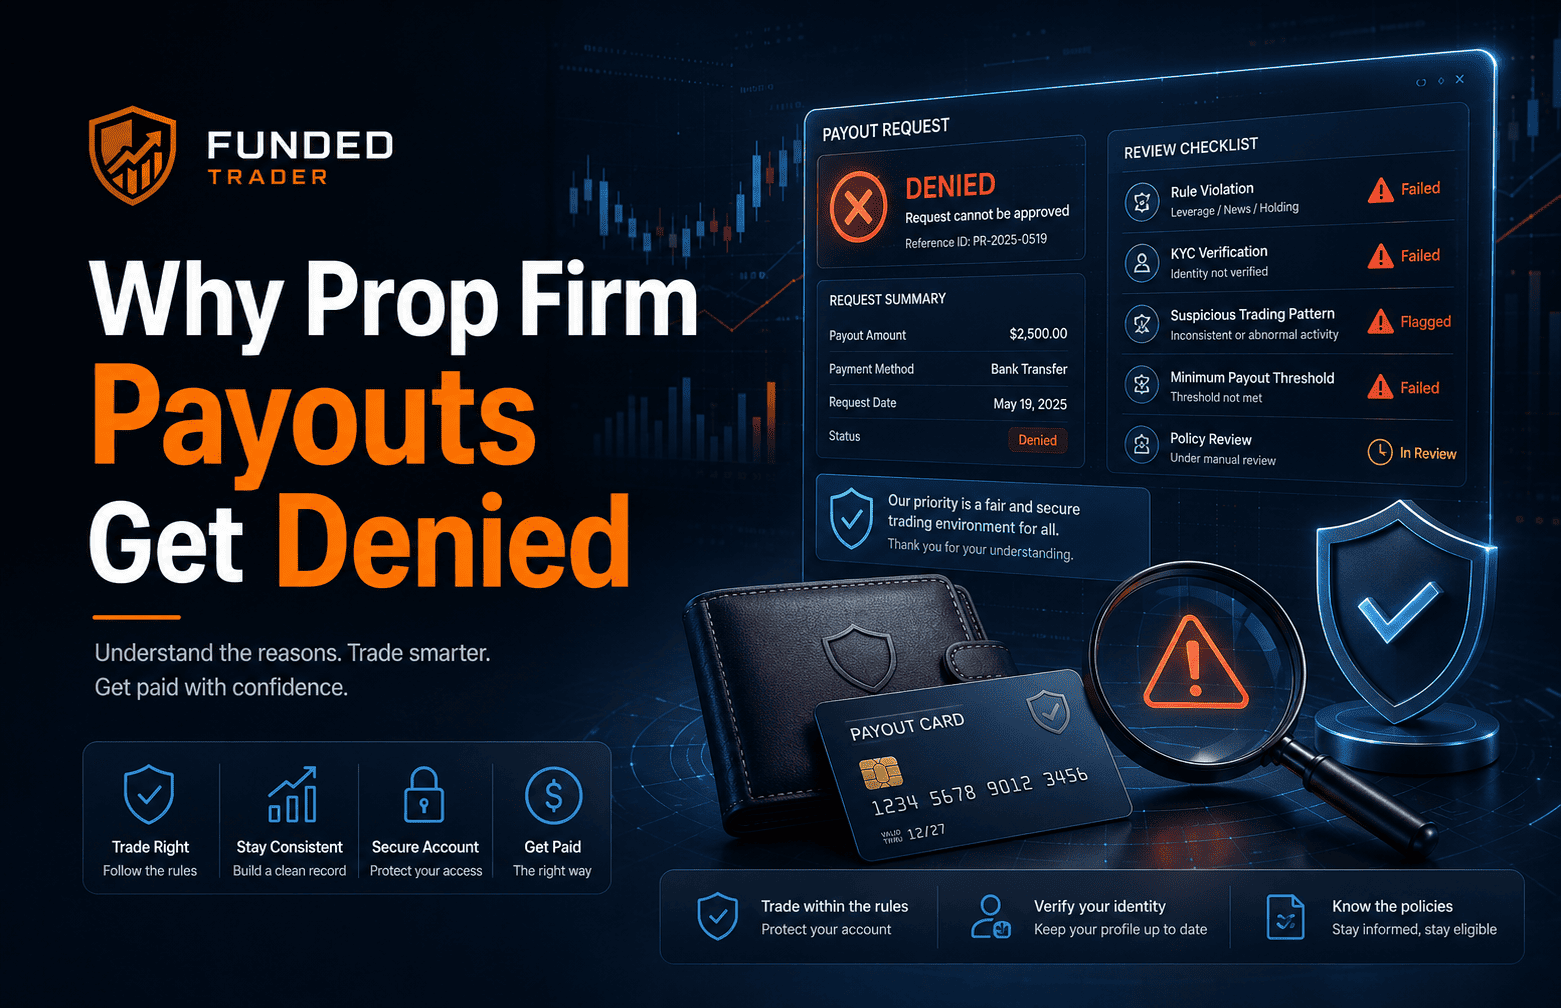

Prop firm payouts are commonly denied, delayed or returned when a profitable account has not met every account-specific payout condition. Profit alone is not enough. The review can include account stage, request timing, minimum amount, identity and payment details, loss limits, consistency rules, permitted trading methods and the amount requested.
A payout result should be diagnosed from the exact programme rules and account record. A clear rule breach, an incomplete request and an unexplained discretionary denial are different problems and require different responses.
This guide focuses on prevention and evidence. For the wider process, start with the Prop Firm Payouts Hub and the first-payout rules guide.
Last rule review: . For AIFO accounts purchased before 1 September 2026, the challenge parameters displayed on the Dashboard apply.
Denied, Delayed, Returned or Not Yet Eligible?
Do not treat every unsuccessful request as a final denial. First identify the status shown by the firm.
| Status | What it means | Next action |
|---|---|---|
| Not yet eligible | At least one timing, minimum-profit, account-stage or programme condition is incomplete | Identify the missing condition and the earliest compliant request point |
| Under review | The firm is checking account status, identity, payment details, trading activity or compliance | Ask which review item remains outstanding |
| Returned | The request or payout details require correction | Correct the stated field and retain both submission records |
| Denied | The firm has decided that the request, account or profit failed an applicable condition | Request the exact rule, calculation, trade IDs and timestamps |
Nine Reasons Prop Firm Payouts Get Denied
| Reason | What can go wrong | Prevention | Evidence to retain |
|---|---|---|---|
| 1. Wrong account stage or request date | The account is profitable but its payout window has not opened | Record the account stage and first eligible request date before trading | Dashboard status, purchase date and payout-cycle rule |
| 2. Request amount is not eligible | The amount is below the minimum, above the per-request maximum or includes profit that must remain | Calculate the eligible amount using the selected programme rules | Balance, eligible profit, requested amount and confirmation screen |
| 3. Identity or payment details are incomplete | Account verification or payout-destination information cannot be approved | Complete and verify payment details before submitting the request | Profile information, verification record and payout details |
| 4. The wrong consistency rule was applied | A concentration limit applies to the account, or the trader assumes a rule applies when it does not | Use only the formula and threshold for the selected account type | Daily P&L, trade-level P&L and the account-specific formula |
| 5. A loss limit was reached | Balance, equity or floating loss reached an account boundary even if the account later recovered | Monitor the applicable Daily, Static, Trailing and floating-loss limits in real time | Trade history, balance, equity and timestamped loss-floor calculations |
| 6. A strategy or tool was not permitted | The platform accepted an order, but the selected programme did not permit the method or tool | Confirm programme eligibility before using an EA or another restricted method | Programme name, rule version, settings and order logs |
| 7. Holding, news or order-state rules were misread | Entries, exits, modifications, pending orders or open positions conflict with the firm’s written rule | Check each action separately instead of assuming all firms treat them alike | Order records, event time, server time and the exact rule text |
| 8. Account access or trade ownership is questioned | The review cannot establish who controlled the account or generated the trades | Keep access, identity and trading decisions attributable to the account holder | Access explanation, account ownership record and trading notes |
| 9. The payout buffer or full-withdrawal rule was misapplied | The request removes an account-specific retained amount or closes the account unexpectedly | Check whether a buffer exists and what a full payout does to that account | Programme rule, requested amount and post-payout balance calculation |
1. Profit Does Not Automatically Create Payout Eligibility
A profit split describes how eligible profit is shared. It does not establish the first request date, minimum request, maximum request or account status.
Before submitting, confirm:
- the exact programme and account stage;
- the standard cycle or on-demand condition;
- the minimum and maximum request amount;
- whether account-specific consistency or buffer rules apply;
- whether the account is still active and compliant.
Do not take low-quality trades only to reach an administrative threshold. That can convert an incomplete request into an account breach.
Current AIFO Payout Rules by Programme
All AIFO account types operate in a simulated trading environment using virtual funds. A payout is a distribution based on eligible simulated trading performance, not a withdrawal of the displayed virtual account balance.
| Programme | Timing and amount | Consistency or concentration | Buffer or closure |
|---|---|---|---|
| 1-Step funded account | $100 minimum; standard 14-day cycle; 80% default split, potentially up to 95% | No Consistency Score requirement | No 2% buffer stated in the account-specific rules |
| 2-Step funded account | $100 minimum; standard 14-day cycle; 80% default split, potentially up to 95% | No Consistency Score requirement | No 2% buffer stated in the account-specific rules |
| Instant | Payout on demand after all applicable conditions; $100 minimum | Maximum single-day profit must be below 20% of payout-period profit | Retain 2% of initial balance to continue; a full payout closes the account permanently |
| Sprint | One payout; request within 30 days after settlement | Largest single-trade profit must be below 20% of total profit | Account closes after the payout |
AIFO’s general payout minimum is $100 and its general maximum is $10,000 per request. Requests are generally processed within 1–3 business days. Compliance review, account verification, payment-channel limitations or unusual account activity may extend that time.
Sprint has a programme-specific processing period of one business day, excluding additional account checks or compliance review. At closed net profit of at least 3% but below 6%, Sprint provides a one-time 90% payout. A closed net profit of at least 6% can qualify for an early 95% payout.
Review the AIFO payout process, AIFO payout rules and AIFO trading rules together.
2. Payment and Account Verification Can Delay a Request
AIFO requires payment details to be completed and saved correctly. Incorrect information can cause a payout delay or returned funds. Processing can also take longer when account verification or compliance review is required.
Check the account-holder information and payout destination before requesting. If a request is returned, correct only the identified issue and preserve the original submission, correction and support response.
3. Consistency Is Account-Specific
A universal consistency claim is inaccurate. The current AIFO rules distinguish the programmes:
- 1-Step and 2-Step funded accounts: no Consistency Score requirement.
- Instant: maximum single-day profit must be below 20% of total profit within the payout period.
- Sprint: largest single-trade profit must account for less than 20% of total profit.
Instant uses a day-level calculation. Sprint uses a trade-level calculation. A trader should not substitute one test for the other. Read the consistency-rule guide for calculation examples.
4. A Recovered Account Can Still Have a Historical Breach
The closing balance does not erase a loss-limit event. A review can use balance, equity, a static loss floor, a trailing HWM-based floor or a floating-loss cap, depending on the programme.
| Programme | Daily Loss Limit | Maximum Loss Limit | Additional boundary |
|---|---|---|---|
| 1-Step | 3% | 6% Static | At least 2 trading days before progression |
| 2-Step | 5% | 10% Static | At least 3 trading days before progression |
| Instant | 3% | 5% Trailing from the highest historical equity, capped at initial balance | Floating loss must not exceed 2% of initial balance |
| Sprint | Programme-specific 24-hour structure | 2% Static | Total floating loss must not exceed 1% of initial balance |
Use the Daily versus Maximum Drawdown guide to keep the calculations separate.
5. EA Permission Depends on the Programme
At AIFO, Expert Advisors are allowed only on 1-Step and 2-Step Challenge accounts and on their corresponding simulated funded accounts after passing.
Instant and Sprint are not included in the current EA eligibility rule. The fact that a platform can execute an automated order does not expand programme permission. Confirm the account type through the AIFO EA policy before trading.
6. Read Holding, News and Order-State Rules Literally
Prop firms may distinguish between opening, closing, modifying or holding a trade, and between an active position and a pending order. These definitions are not interchangeable across firms or programmes.
Before trading around an event or submitting a payout request, record the applicable rule and server time. For AIFO, confirm any news or holding condition in the current written rules for the selected account.
For general preparation, see the guides to news trading and overnight and weekend holding.
7. Preserve Evidence of Account Control and Trade Ownership
If a firm questions account access or the origin of trades, a vague explanation is weaker than contemporaneous evidence. Preserve the account owner information, relevant access explanation, trade plan and order history.
Do not assume that a method permitted by one firm is permitted by another. The selected programme’s written rule must control the decision.
8. The 2% AIFO Buffer Applies Only to Instant
AIFO Instant requires the account to retain profit equal to at least 2% of the initial account balance after payout if the trader wants to continue using the account.
An Instant trader may request all available profit, including the buffer. That full payout permanently closes the account and it cannot be restored.
Do not apply the Instant buffer to 1-Step, 2-Step or Sprint. Their current account-specific sections do not establish that 2% retained-profit rule.
9. An Unexplained Denial Requires an Evidence-Based Appeal
A review is auditable when the firm identifies the applicable rule, account calculation, affected trade and time. A statement such as “risk review failed” is not enough for the trader to reproduce the decision.
If the reason is unclear, request:
- the exact rule and version used;
- the calculation and account metric;
- the affected trade IDs and server timestamps;
- the account status before and after the request;
- the available escalation or reconsideration process.
A firm that supplies a reproducible reason allows the trader to verify or challenge the result. Repeatedly changing the explanation is a governance warning. See how to assess whether a prop firm is legitimate.
What to Do Immediately After a Payout Is Denied
- Stop changing the account state. Do not place new trades until the reason and consequences are clear.
- Save the evidence. Capture the dashboard, balance, equity, request status, trade history and applicable rules.
- Request a precise explanation. Ask for the clause, calculation, trade IDs and timestamps.
- Recalculate independently. Use the correct programme’s loss, consistency and buffer rules.
- Separate correction from dispute. Fix an incomplete payment field, but challenge a calculation only with evidence.
- Decide whether to continue. A transparent correction process differs from an unauditable denial.
Pre-Request Payout Checklist
- Confirm the current programme and account stage.
- Confirm that the account uses the current rule version.
- Check the first eligible request date and applicable payout cycle.
- Check the $100 AIFO minimum and $10,000 general per-request maximum.
- Complete and verify payment details.
- Recalculate every applicable Daily, Maximum and floating-loss boundary.
- Apply no Consistency Score to 1-Step or 2-Step funded accounts.
- Apply the below-20% single-day test only to Instant.
- Apply the below-20% largest-single-trade test to Sprint.
- Use EAs only on eligible 1-Step and 2-Step accounts.
- Apply the 2% retained-profit buffer only to Instant.
- Save the request confirmation and account-state evidence.
Final Takeaway
A payout request is a review of eligibility and account history, not merely a request to remove visible profit. Most preventable problems come from applying the wrong programme rule, requesting at the wrong time, submitting incorrect payment details or failing to preserve evidence.
For AIFO, keep the boundaries precise: all accounts are simulated; 1-Step and 2-Step funded accounts have no Consistency Score; Instant alone has the mandatory 2% retained-profit buffer; and EA permission is limited to 1-Step and 2-Step Challenge accounts and their corresponding simulated funded accounts.
Frequently Asked Questions
Payouts can be denied when a profitable account does not meet its account-specific timing, amount, verification, loss, consistency, strategy or buffer requirements. The firm should identify the exact rule, calculation and account record behind a denial.
No. A denial may result from a clear rule breach, an incomplete request or failed verification. It becomes a serious governance warning when the firm cannot provide a consistent, reproducible explanation using the written rule and account evidence.
No. The current AIFO rules state that 1-Step and 2-Step funded accounts have no Consistency Score requirement. Instant and Sprint use separate profit-concentration tests that must not be applied to 1-Step or 2-Step.
Yes, if an EA is used on an ineligible programme. AIFO permits Expert Advisors only on 1-Step and 2-Step Challenge accounts and on their corresponding simulated funded accounts after passing. Instant and Sprint are not included in that permission.
No. The mandatory 2% retained-profit buffer applies only to Instant Accounts. A full Instant payout including that buffer permanently closes the account. The rule must not be added to 1-Step, 2-Step or Sprint.
AIFO payout requests are generally processed within 1–3 business days. Sprint uses a programme-specific one-business-day processing period, excluding additional account checks or compliance review. Other reviews or payment-channel limitations can extend processing.
Stop changing the account state, save the dashboard and trade records, and request the exact rule, calculation, trade IDs and timestamps. Recalculate the result using the selected programme’s rules before correcting the request or filing an evidence-based dispute.